Full platform
Core, channels, journeys, integration and operations as one turn-key delivery.
Microfinance companies, finance companies, new digital banks
For banks, microfinance companies and fintechs in the MENA region
neotra gives licensed lenders a core that launches a new loan or savings product by configuration, connects to CliQ, eFAWATEERcom and CRIF Jordan, and targets go-live in 12 to 16 weeks.
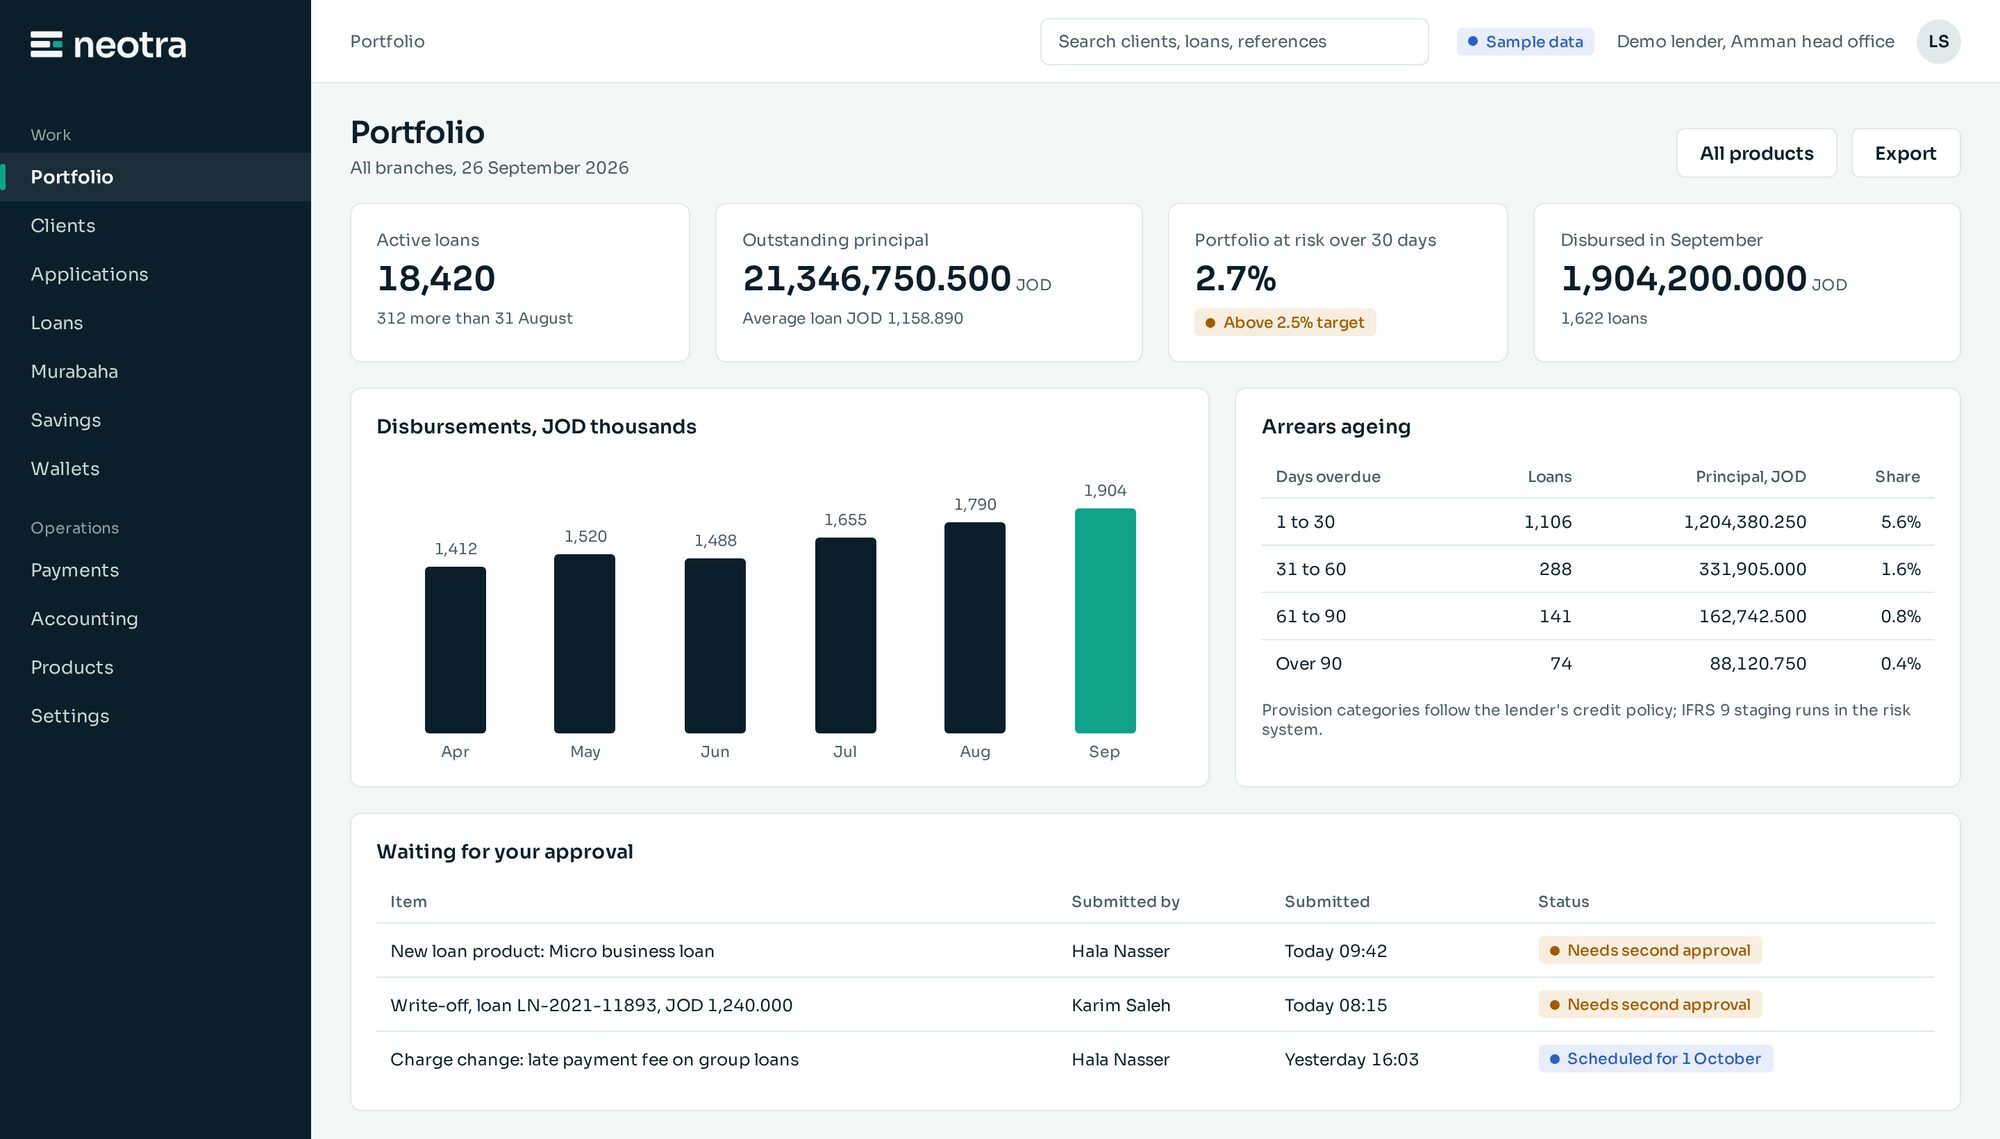
neotra is a modular banking platform: a core system of record for customers, loans, deposits and the general ledger, plus the channels, customer journeys, operations tools, integration layer and AI services an institution needs around it. Every module except card processing, AML monitoring and IFRS 9 provisioning is designed and built by the neotra team.
Choose the modules that close today's gaps, prove them on one product line or one channel, then extend.
Core, channels, journeys, integration and operations as one turn-key delivery.
Microfinance companies, finance companies, new digital banks
The core with the modules the institution chooses, for example mobile app and onboarding.
Fintechs, e-wallets and BNPL providers
A mobile app, onboarding, gateway or product engine connected to the bank's current core.
Established banks keeping their system of record
Core, mobile app, onboarding, gateway, operations console and payment reconciliation come from one team, one support contract and one set of APIs.
Schedule, profit or interest method, tenor, grace, charges and the ledger accounts each event posts to are defined in the operations console. A second officer approves, and it is live without a code release.
Beside an existing core, the current book stays where it is. neotra starts with one product line or channel, posts a daily summary to the incumbent GL and reconciles at end of day.
Every command is checked against role permissions, can require a second approver, and is written to an audit trail with user, time and before and after values. Every posting is a balanced double entry.
Arabic and English throughout, multi-currency accounts held to the smallest unit, central bank reporting extracts, and connectors to national payment rails, the credit bureau and the national digital ID.
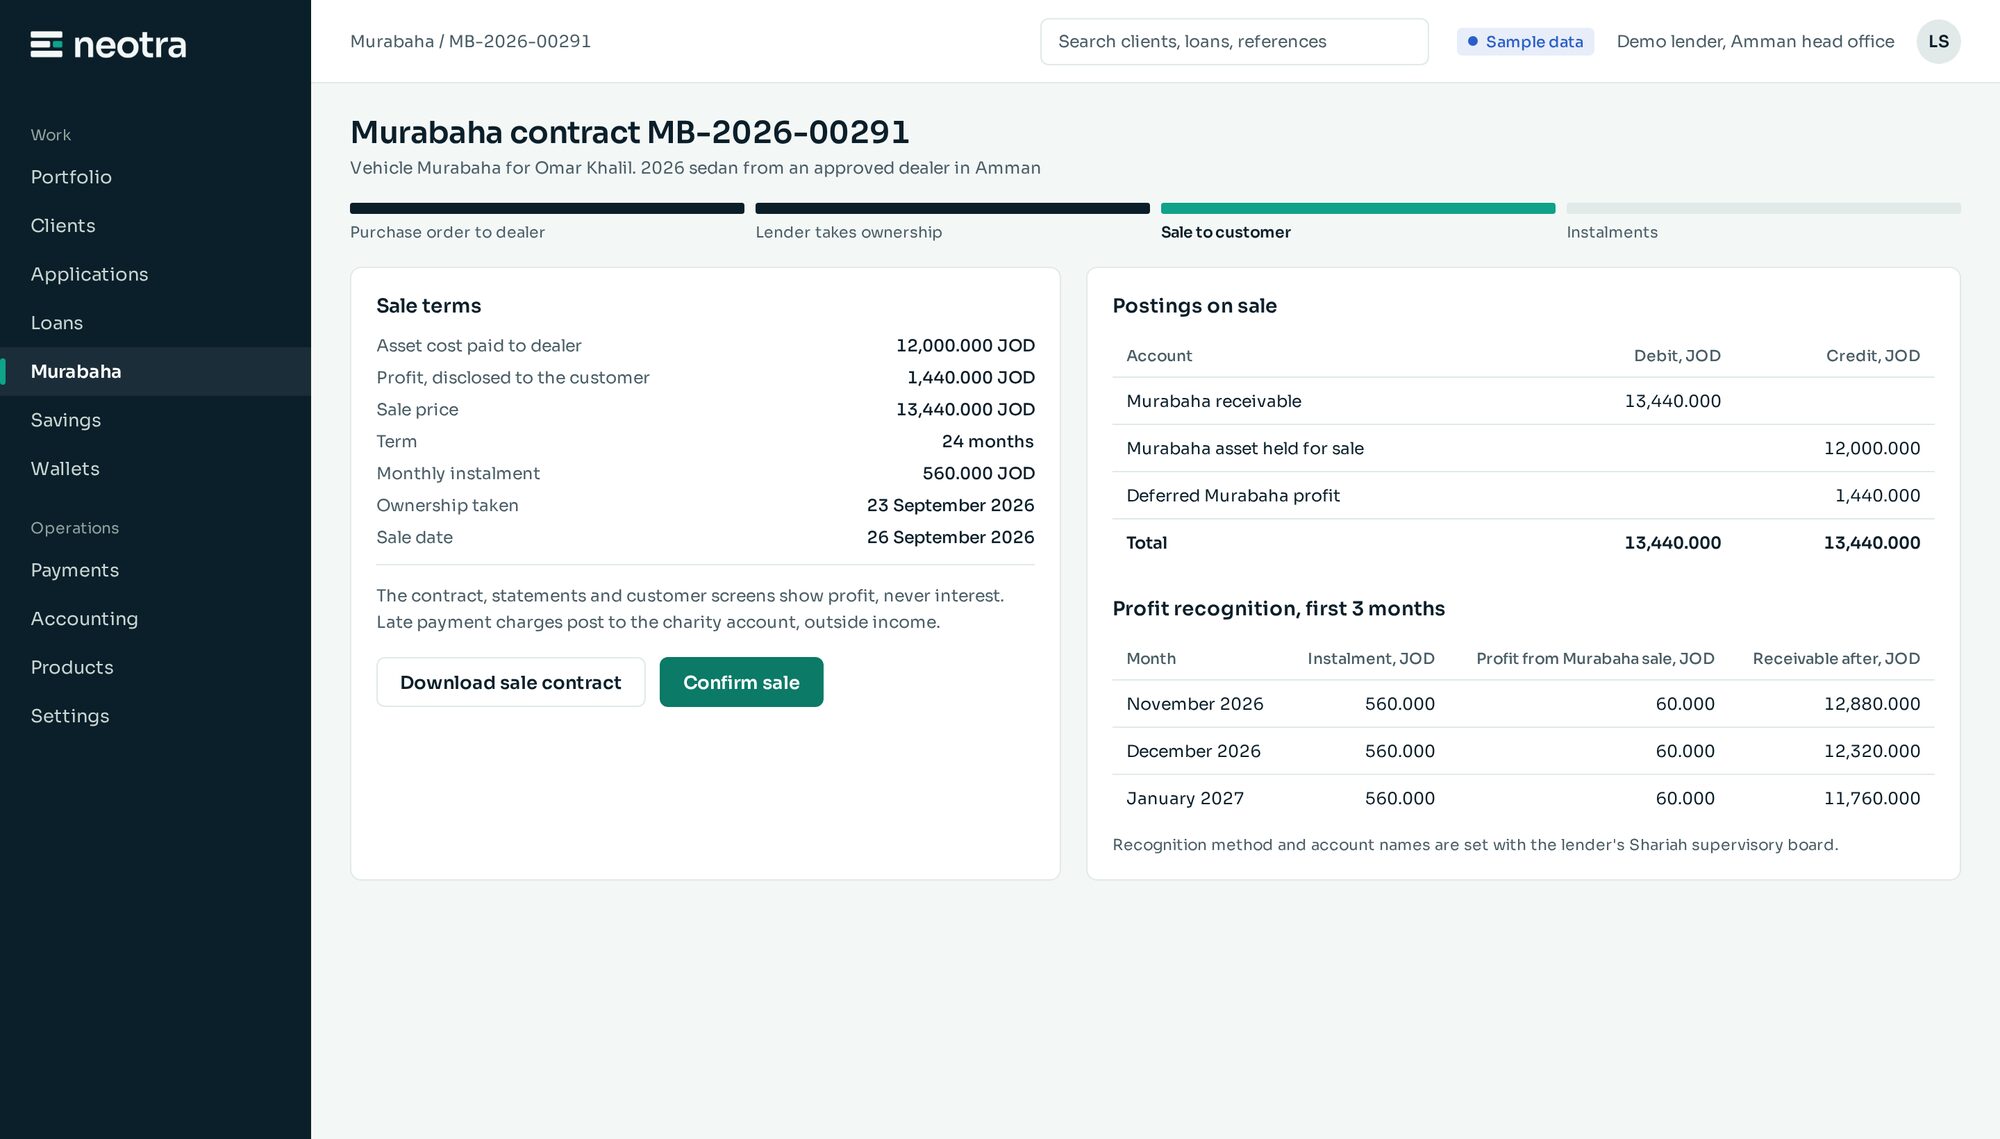
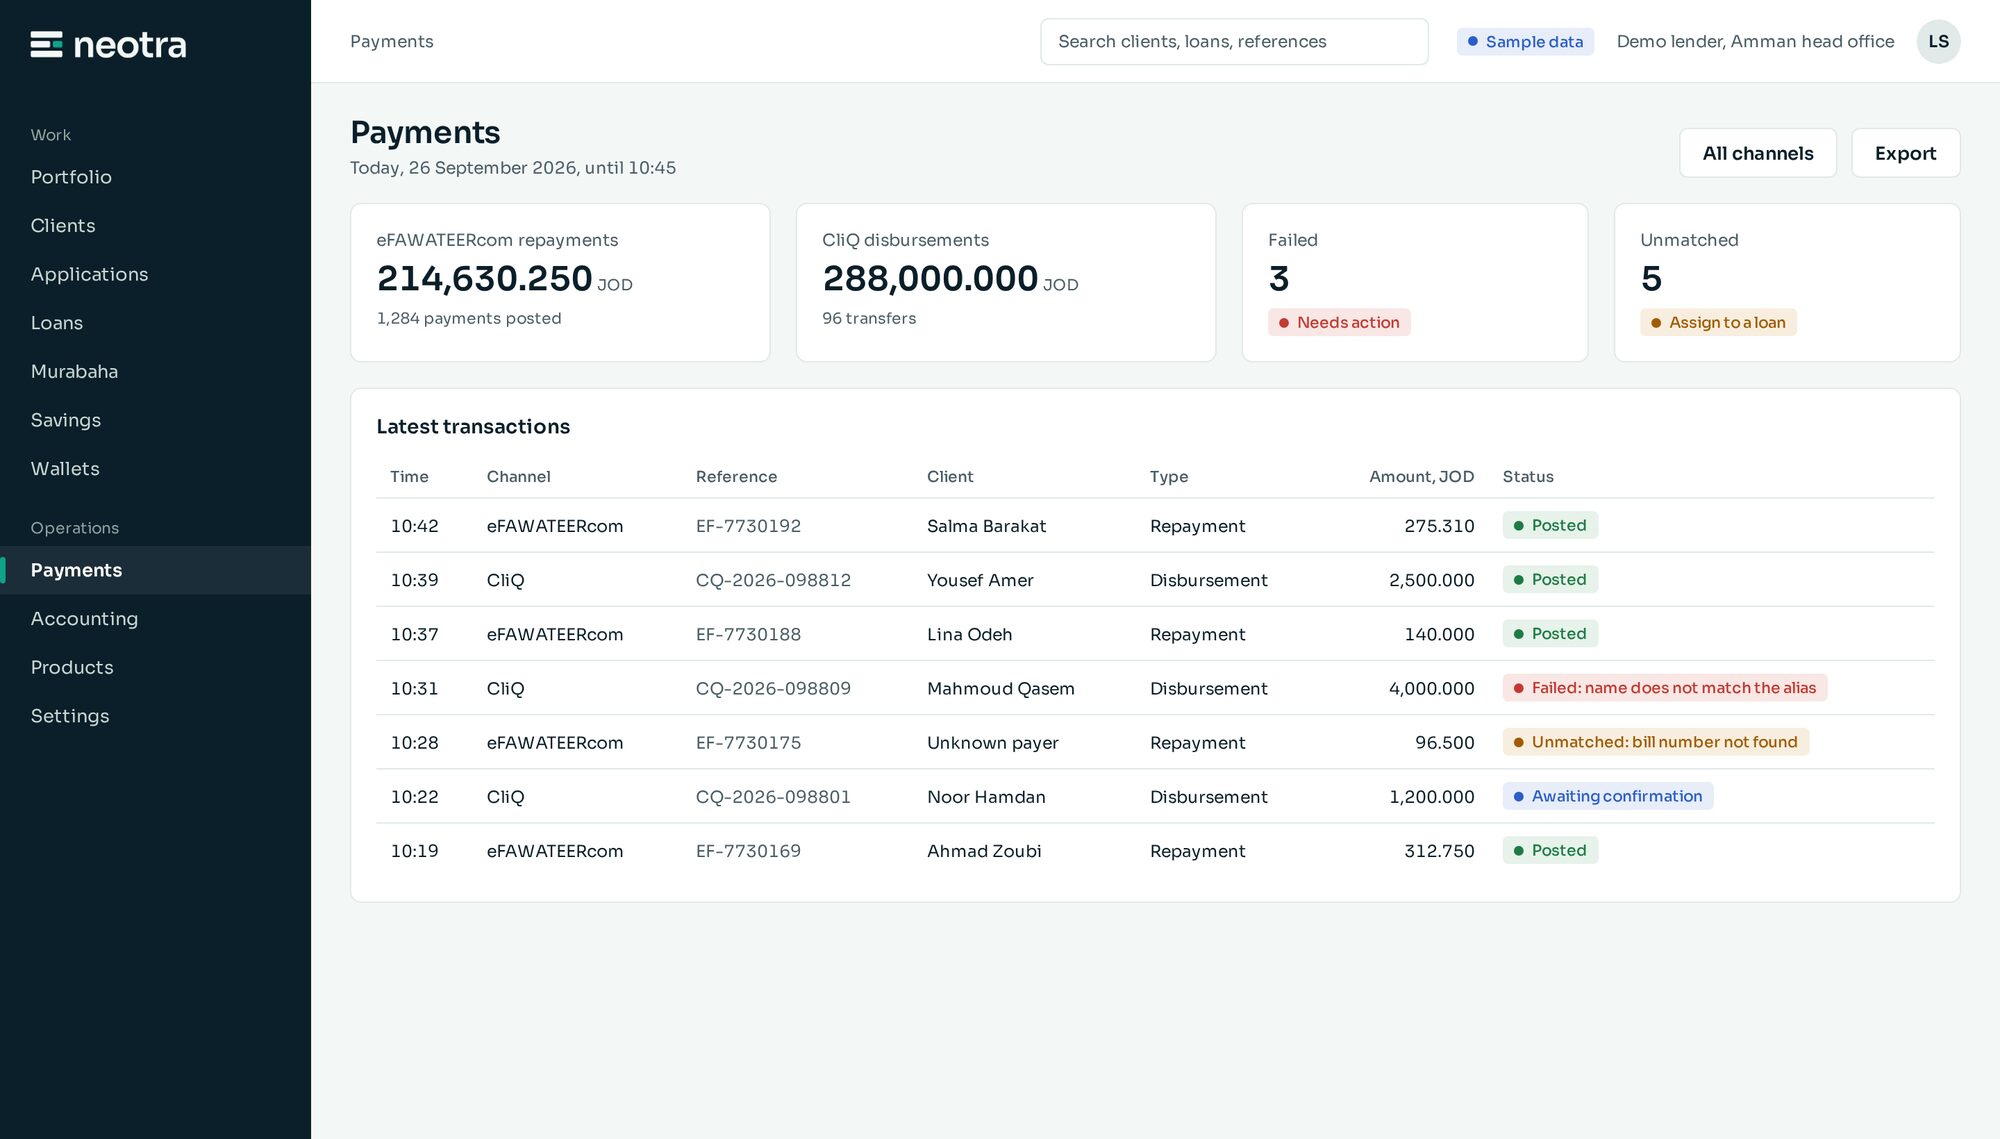
Each connector goes live after sandbox certification with its operator.
Modules, product rules, GL design, integrations, deployment option and the pilot's exit tests are agreed in writing.
The selected modules go live in a pilot environment with real rails in sandbox, then with a controlled customer group.
Further products are added by configuration and further modules by release, against the same exit tests.
neotra is a lending, savings and wallet core and modular banking platform for licensed financial institutions in the MENA region. It is a product of BRDG Studio in Amman, Jordan.
Microfinance companies, specialised finance companies, e-wallets, buy-now-pay-later providers, and banks that want to launch new products beside their incumbent core.
No. In product engine mode neotra runs beside the incumbent core. The current book stays where it is, and neotra posts a daily summary to the incumbent general ledger and reconciles it.
Discovery takes 2 to 4 weeks, followed by a 12 to 16 week pilot. After go-live, a new product launches by configuration in under one working day.
Yes. Murabaha, Qard Hasan and Wadiah current accounts are in the core; Ijara Muntahia Bittamleek, Diminishing Musharaka, Istisna, Mudaraba and Wakala are modules. Each is approved by the institution's Shariah supervisory board.
In an in-country cloud region or a jurisdiction the regulator accepts, or on-premises in the institution's data centre, with the same software and upgrade path.
neotra runs on a hardened, commercially supported distribution of the Apache Fineract ledger engine, extended with proprietary neotra modules.
With your business, finance, IT and Shariah teams, we select the modules, the first product line and the pilot's exit tests.